

Confidentiality
Confidentiality in the sale of a business
Premature disclosure can damage the very business being sold. The practices below describe how we control the flow of information from the first conversation through closing.
Why confidentiality matters
A business depends on the continued confidence of its employees, customers, suppliers and lenders. News of a pending sale can unsettle each of those relationships at precisely the time buyers are scrutinizing performance, and the damage does not reverse if the transaction fails to close.
A controlled process is the most reliable protection. We follow the same practices on every engagement, and they serve buyers as well as sellers, since both have an interest in preserving the value of the business until closing.
The same discretion applies when we advise an acquirer. A buyer’s criteria, targets, offers and lender discussions are not shared outside the engagement.
Independence
Twelve31 Advisors, LLC is the advisory business of Twelve31. When we represent a buyer or seller, we work for that client alone. We don’t use what a client shares with us to acquire a business for Twelve31 or its affiliates. If an advisory client’s business could ever be of interest to a Twelve31 affiliate as a buyer, we tell the client in writing first, and nothing proceeds without their written consent. Client information stays confidential under our engagement terms and NDA.
Who is affected by premature disclosure
 (opens a larger view)
- EmployeesUncertainty about job security can prompt departures and erode morale and performance.
- CustomersCustomers may question continuity of service after a sale and move their business elsewhere.
- SuppliersSuppliers may shorten payment terms or limit credit, which strains working capital and, in turn, value.
- CompetitorsCompetitors may use the news to approach your customers and employees.
- LandlordsAn uncertain landlord may be reluctant to cooperate with a prospective buyer on the lease.
- CreditorsLenders may hesitate to extend new credit, with consequences for cash flow and profitability.
How we maintain confidentiality
Both parties have an interest in preserving the value of the business through closing. These practices apply to every engagement.
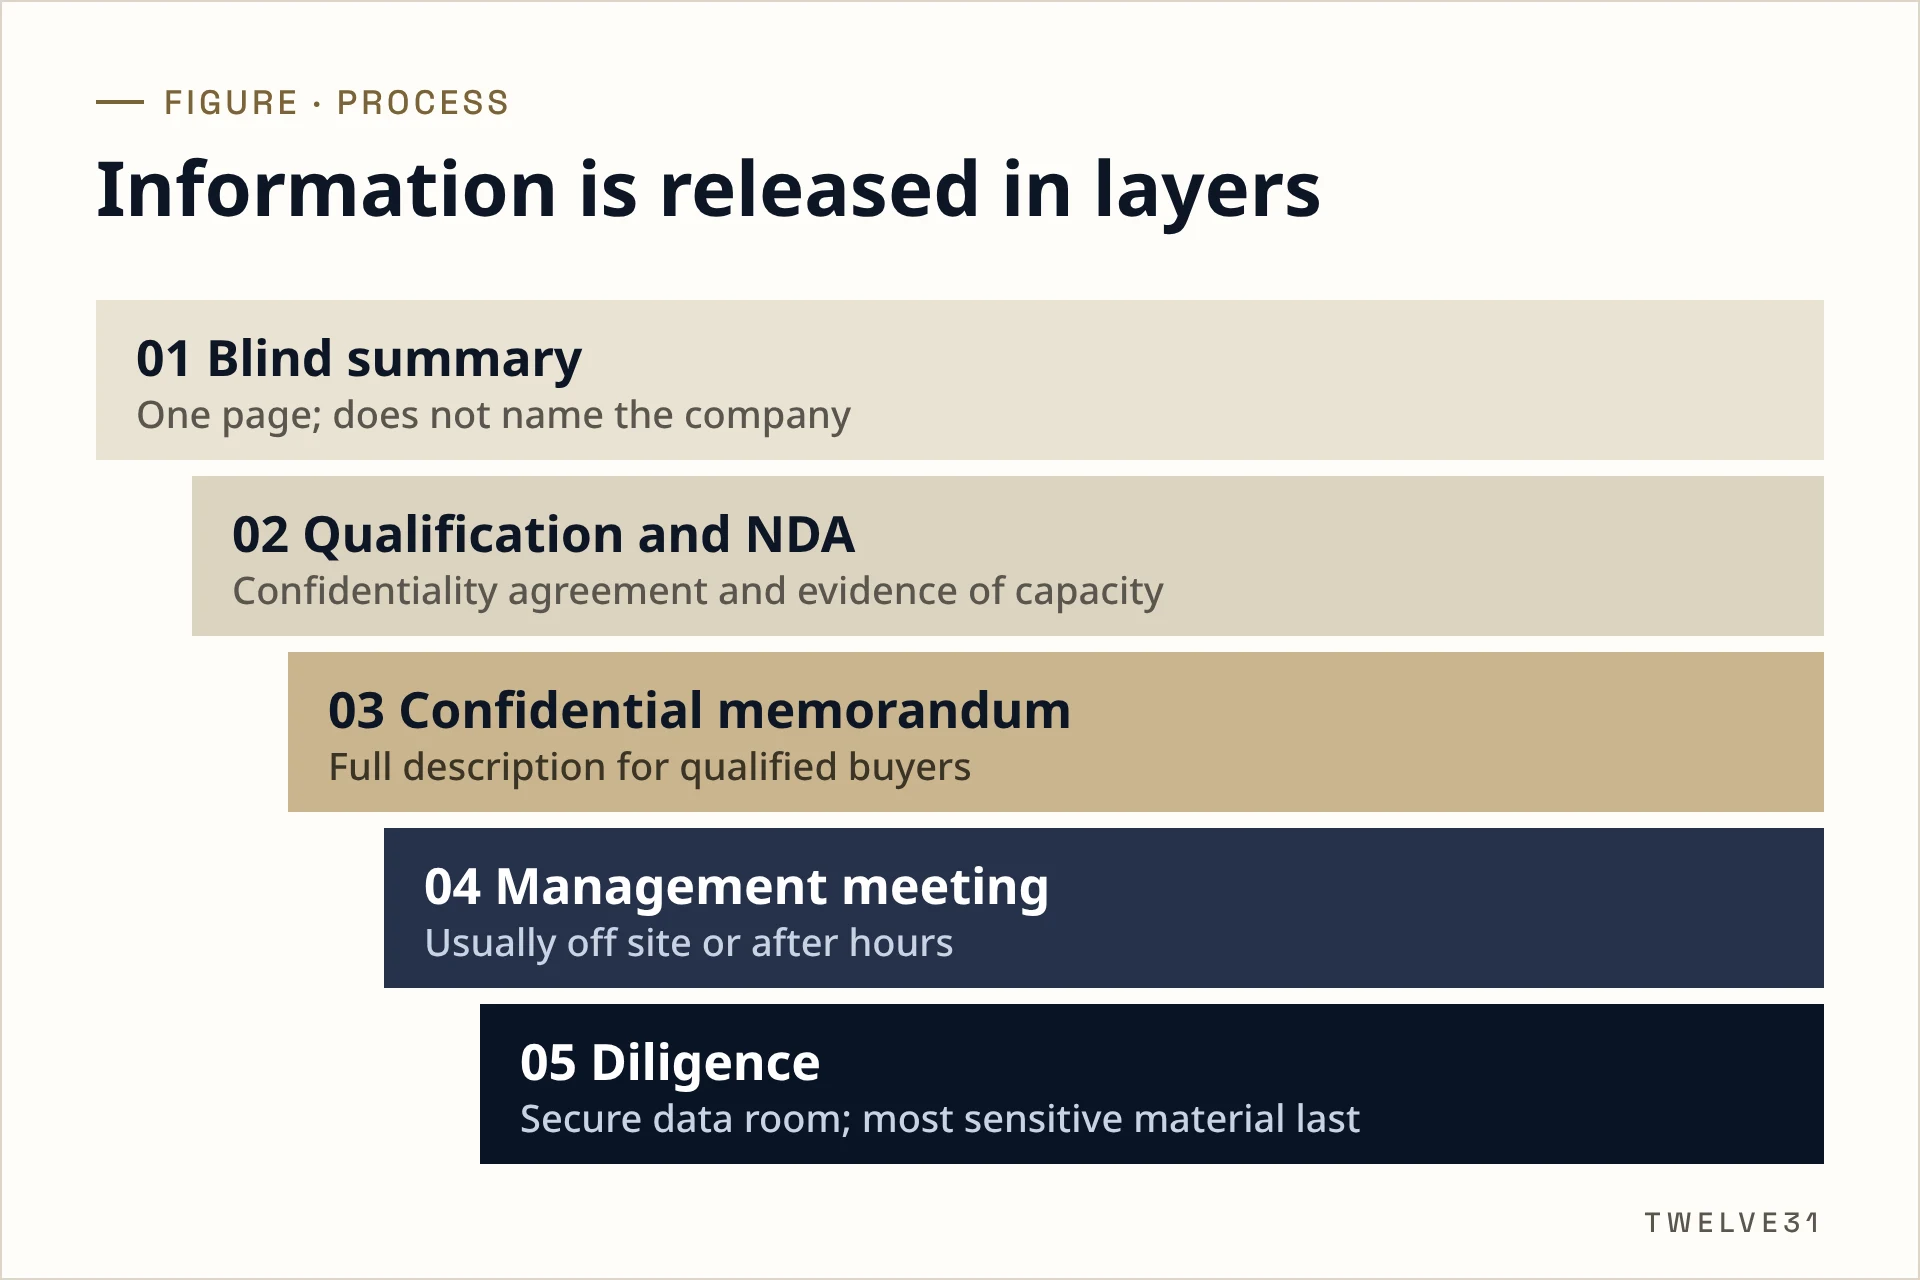
- Blind marketingOutreach materials limit identifying information. The location and other sensitive details are disguised, and the business is never advertised on public marketplaces or business-for-sale websites.
- Qualified buyersBuyers are evaluated financially and operationally before they receive confidential information about your business.
- Confidentiality agreement firstEvery buyer signs a confidentiality agreement before the company is identified, which prohibits disclosure of any information about the business or its sale.
- Buyer profileBuyers also provide a summary of their experience and financial capacity, which tells you who you are dealing with and screens out parties that are not prepared to transact.
- Need to knowOnly those with a direct role, typically your attorney and CPA, are informed of your plans.
- Staged informationBuyers receive the information appropriate to each stage, such as revenue and earnings history early in the process and customer detail later.
- Protected documentsProprietary processes, tax returns, detailed financial statements and customer lists remain confidential until the appropriate stage.
- Sensitive information lastThe most sensitive information is released late in diligence, and only when it is required to close.
- No contact with employeesBefore closing, buyers communicate with you and with us, not with your employees. A premature conversation can cost the business a key person.
- A plan for key employeesKey employees are informed at the appropriate time, with a plan to retain them after the sale. Confidentiality, retention or employment agreements can support that plan.
Advisory
More from our advisory practice
Advisory overview
Buy-side representation first, with sell-side advisory for owners.
Explore
Buy-side representation
Our principal practice: advising acquirers from target screen to funded closing.
Explore
Sell-side advisory
Focused, confidential sale processes for owners of established companies.
Explore
Valuation and deal structure
Normalized earnings, supportable value and structures a lender will fund.
ExploreConfidential, with no obligation
Begin with a confidential conversation
Nothing you share with us is disclosed without your consent.
- Or call402-957-1231
- Office1001 Farnam Street, Suite 201, Omaha, NE 68102